window.dataLayer = window.dataLayer || []; function gtag(){dataLayer.push(arguments);} gtag('js', new Date()); gtag('config', 'UA-165322976-1');
17 Sep 2026

Maximize Your Exit with an IRS Section 453 Deferred Sales Trust

By |2026-09-18T13:36:14+00:00September 17th, 2026|Categories: Selling a Business|Tags: , , , , , |

Maximize Your Exit with an IRS Section 453 Deferred Sales Trust

When preparing to sell a business, most owners focus almost entirely on negotiating the highest possible purchase price. While securing a strong valuation is vital, what you keep after taxes determines the true success of your exit.

A traditional cash sale creates a massive tax event. Immediate federal capital gains taxes, state taxes, and surtaxes can permanently erode 20% to 30% or more of your hard-earned equity at closing. Once that capital is paid to tax authorities, it is gone forever and can no longer generate returns or compound for your future.

What is an IRS Section 453 Deferred Sales Trust (DST)?

An IRS Section 453 Deferred Sales Trust (DST) is a tax-planning strategy that leverages the IRC Section 453 installment sale framework to defer capital gains taxes. Instead of selling your company directly to a buyer in exchange for a single lump-sum payout, you sell the asset to an independent third-party trust. The trust then executes the sale to the buyer and pays you over time through a structured installment note, allowing you to delay your tax obligation until cash is actually distributed.

How the DST Structure Works

  1. Transfer the Asset: Prior to closing, you transfer your business equity or qualifying asset to an irrevocable trust managed by an independent trustee.
  2. Trust Completes the Sale: The trust sells the business to the end buyer for the negotiated purchase price and holds the sale cash in dedicated accounts.
  3. Issuance of Promissory Note: In exchange for your asset, the trust provides you with a formal promissory note (often structured for up to 30 years).
  4. Deferred Tax Recognition: You only pay capital gains taxes on the principal portion of the note payments as you physically receive them each year.

Key Benefits for Selling Owners

  • No Reinvestment Rules: Unlike a 1031 real estate exchange, you are not subject to strict like-kind replacement rules or tight 45-day/180-day purchase windows.
  • Investment Freedom: The trust can reinvest the sale proceeds into a diversified portfolio of growth assets, fixed income, or commercial income-producing real estate.
  • Flexible Payout Structure: You retain the flexibility to customize your note terms—such as receiving interest-only distributions targeted at 8% to 10% annually—to strategically manage your annual tax bracket.

The Math: A $5M Case Study

Consider a business owner selling a company for $5,000,000:

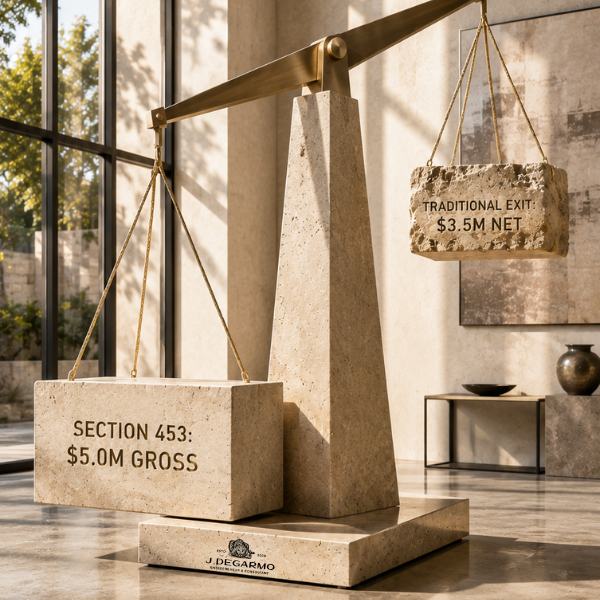
  • Under a Traditional Sale: The owner pays immediate federal capital gains and surtaxes, shrinking the investable principal down to roughly 3.5M–3.8M on day one. Future investment returns compound only on this reduced net amount.
  • Under a Structured Section 453 DST Exit: Capital gains recognition is deferred. The entire $5,000,000 gross purchase price remains deployed. Earning an annual yield on the full $5M principal produces significantly higher cumulative cash flow and long-term wealth compared to investing net proceeds after upfront taxes.

Risks and Compliance Considerations

While a Section 453 DST is a powerful wealth-preservation vehicle, it requires precise legal and tax execution:

  • Branded Strategy, Not an IRS Acronym: “Deferred Sales Trust” is a financial product name, not a formal term in the Internal Revenue Code. The structure relies directly on core Section 453 installment sale rules.
  • Strict Trustee Independence: The trustee must be entirely independent. If you retain direct control over the trust’s bank accounts or investment selections, the IRS can invoke the “constructive receipt” doctrine and demand immediate payment of all capital gains taxes.
  • IRS Scrutiny: Tax authorities closely examine installment arrangements. The entire process must maintain genuine economic substance and be fully established before binding purchase contracts are finalized.

Why You Need an M&A Advisor to Execute This Strategy

Structuring a transaction for maximum after-tax value requires far more than listing your company on the market. It demands an advisory team that understands how to coordinate with qualified trustees, tax attorneys, and CPA specialists well before closing agreements are signed.

As your business broker, my role extends beyond finding the right buyer. I guide you through advanced transaction design, ensuring your deal is structured for maximum capital efficiency, full tax compliance, and long-term wealth preservation.

Contact me today to discuss how we can position your company for sale while protecting your proceeds through structured exit strategies.
Maximize Your Exit with an IRS Section 453 Deferred Sales Trust
10 Sep 2026

Navigating the Franchise Resale: Why It’s a Completely Different Beast

By |2026-07-29T20:19:46+00:00September 10th, 2026|Categories: Selling a Business|Tags: , , , , |

Navigating the Franchise Resale: Why It’s a Completely Different Beast

Navigating a franchise resale is an entirely different beast than handling a traditional, independent business sale. In a standard transaction, your primary circle consists of the buyer, the seller, their respective attorneys, a lender, and the brokers. But when a franchise is involved, a powerful third party enters the mix: the franchisor.

Because the franchisor holds ultimate veto power over who can take over the business, treating a franchise resale like a standard street listing is a recipe for broken deals and massive delays. If you want to survive the transfer process and protect the transaction, you must adjust your approach to handle the extra layers of corporate complexity.

The Franchise Shift: What Changes in a Resale?

While a standard business broker focuses primarily on matching a buyer and seller, a franchise resale requires managing three distinct interests simultaneously.

Think of it this way: your primary job is still to structure a fair financial deal, but you must constantly vet every move against the franchisor’s rigid corporate rulebook.

Here is how a franchise resale compares to a traditional independent sale across key areas:

  • Primary Approval: Independent sales only require buyer and seller agreement, whereas franchise resales give mandatory veto power to the franchisor.
  • Upfront Friction: Standard deals focus heavily on negotiating the purchase price, while franchise deals require buyers to meet strict net worth and liquidity minimums set by the corporate office.
  • Hidden Capital Costs: Independent sales mainly deal with working capital allocations, but franchise transactions often introduce unexpected transfer fees and mandatory facility upgrades.
  • Closing Timeline: Independent deals typically wrap up in 60 to 90 days, whereas franchise resales frequently stretch out to 120 to 180 days (or longer).

Why You Must Align with the Franchisor Early

One of the most critical steps happens before you even take on the formal engagement: you need to align with the franchisor. Relying solely on the seller’s memory or outdated paperwork can lead to nasty surprises—like discovering the original agreement is misplaced or that the rules have completely shifted.

Get a meeting early to clarify:

  • Minimum Buyer Qualifications: Franchisors often enforce strict net worth or liquid capital minimums that have nothing to do with the actual purchase price. If a buyer can easily finance the deal but fails the franchisor’s baseline asset requirement, the deal is dead on arrival.
  • Operational Requirements: Does the franchisor require the owner to be a hands-on manager, or do they allow passive investment? Some brands require new owners to personally run daily operations for the first six months, which immediately disqualifies pure financial investors.

Uncovering the “Second Check” Problems

In an independent sale, the purchase price is typically the final word. In a franchise resale, everyone needs to know exactly what it costs to cross the finish line. Keep an eye out for these financial hurdles:

  • Transfer Fees: Transferring an existing contract usually incurs a hefty fee, frequently matching 50% of the initial franchise fee. Alternatively, the franchisor might mandate a brand-new 10-year agreement with full upfront fees. Clear up who is writing this check right away so it can be factored cleanly into the purchase price.
  • Mandatory Remodeling: Franchisors routinely mandate structural or aesthetic upgrades upon a transfer. If a location hasn’t been updated in a decade, the buyer might face a mandatory six-figure renovation bill immediately after closing.
  • Training Expenses: Buyers are almost always on the hook for travel and lodging expenses during mandatory corporate training programs.

Pro Tip: If a seller insists they won’t cover the transfer fees even though their contract says they must, consider adjusting the total listing price upward to cover the cost. This allows the buyer to finance the transfer fee through their acquisition loan rather than burning through liquidity.

Adjust Your Deal Timeline for the Bureaucratic Black Hole

Franchise resales take significantly longer to close than standard business sales. If your typical independent deal closes in 8 weeks, budget at least 16 weeks for a franchise transaction.

Two primary factors slow down momentum:

  • Mandatory Cooling-Off Periods: In many regions, regulatory laws mandate a strict two-week “cooling-off” period once the official disclosure documents are handed to a prospective buyer. During this window, all formal sales communications pause so the buyer can review the legalities without pressure. This instantly adds two static weeks to your timeline.
  • Bureaucratic Bottlenecks: Large corporate systems often have a single representative or a small department managing every single resale across an entire country. If your transaction gets buried at the bottom of a corporate queue, your deal can stall in a communication black hole for weeks on end.

The 2026 Resale Reality: Market Both the Cash Flow and the System 

When it comes to positioning the listing, remember that a franchise resale offers a dual value proposition. You aren’t just selling a historical stream of cash flow; you are selling a vetted, operational cheat code.

Highlight the built-in marketing machine, established supply chains, and structured training programs. This combination inherently lowers the failure rate compared to independent startups, making it highly attractive to ambitious, first-time entrepreneurs or expanding multi-unit operators who value scale over creative control. Keep the franchisor in the loop, eliminate surprises early, and prepare both parties for a longer operational runway.

Let’s Secure Your Next Franchise Transition 

Taking on a franchise resale requires a specialized playbook, but the rewards of transferring a highly structured, profitable brand are immense. By pairing clear upfront communication with a deep understanding of corporate guidelines, you can guide buyers and sellers seamlessly through the transfer process.

Contact me to discuss how to strategically prepare your franchise location for a successful, high-value sale.

Navigating the Franchise Resale: Why It’s a Completely Different Beast
5 Mar 2026

Asset Sale vs. Stock Sale: Tax Implications for Business Sellers (2026)

By |2026-03-04T16:57:29+00:00March 5th, 2026|Categories: Selling a Business|Tags: , , |

Asset Sale vs. Stock Sale: Tax Implications for Business Sellers (2026)

When you sell your business, don’t just focus on the highest offer. Your sale structure changes your final “walk-away” amount. Just like choosing an entity type, the structure impacts your taxes.

What is the difference for a seller?

Most small business deals use asset acquisitions. In an Asset Sale, buyers purchase specific items like equipment, inventory, and goodwill. Buyers prefer this because they can re-depreciate your equipment.

However, an asset sale can become a tax trap for you. Hard assets often trigger “depreciation recapture.” This is taxed at high ordinary income rates. C-Corps may also face double taxation on these sales.

In a Stock Sale, the buyer purchases your entity’s shares directly. Most sellers prefer this route. The proceeds usually qualify for favorable long-term capital gains rates. Active owners might even avoid the 3.8% Net Investment Income tax.

So, what is the right choice?

The best choice depends on your entity type and your assets. Stock sales are cleaner and more tax-efficient for you. Conversely, buyers may insist on asset sales to avoid your past liabilities.

The IRS requires both parties to report identical details on Form 8594. You should agree on these details before closing. Always consult an M&A tax professional to protect your money.

Next Steps

Let’s discuss your specific situation and explore the potential benefits of selling your business. You can reach me directly here to start the conversation.

Asset Sale vs. Stock Sale: Tax Implications for Business Sellers (2026)
Go to Top