Maximize Your Exit with an IRS Section 453 Deferred Sales Trust
When preparing to sell a business, most owners focus almost entirely on negotiating the highest possible purchase price. While securing a strong valuation is vital, what you keep after taxes determines the true success of your exit.
A traditional cash sale creates a massive tax event. Immediate federal capital gains taxes, state taxes, and surtaxes can permanently erode 20% to 30% or more of your hard-earned equity at closing. Once that capital is paid to tax authorities, it is gone forever and can no longer generate returns or compound for your future.
What is an IRS Section 453 Deferred Sales Trust (DST)?
An IRS Section 453 Deferred Sales Trust (DST) is a tax-planning strategy that leverages the IRC Section 453 installment sale framework to defer capital gains taxes. Instead of selling your company directly to a buyer in exchange for a single lump-sum payout, you sell the asset to an independent third-party trust. The trust then executes the sale to the buyer and pays you over time through a structured installment note, allowing you to delay your tax obligation until cash is actually distributed.
How the DST Structure Works
- Transfer the Asset: Prior to closing, you transfer your business equity or qualifying asset to an irrevocable trust managed by an independent trustee.
- Trust Completes the Sale: The trust sells the business to the end buyer for the negotiated purchase price and holds the sale cash in dedicated accounts.
- Issuance of Promissory Note: In exchange for your asset, the trust provides you with a formal promissory note (often structured for up to 30 years).
- Deferred Tax Recognition: You only pay capital gains taxes on the principal portion of the note payments as you physically receive them each year.
Key Benefits for Selling Owners
- No Reinvestment Rules: Unlike a 1031 real estate exchange, you are not subject to strict like-kind replacement rules or tight 45-day/180-day purchase windows.
- Investment Freedom: The trust can reinvest the sale proceeds into a diversified portfolio of growth assets, fixed income, or commercial income-producing real estate.
- Flexible Payout Structure: You retain the flexibility to customize your note terms—such as receiving interest-only distributions targeted at 8% to 10% annually—to strategically manage your annual tax bracket.
The Math: A $5M Case Study
Consider a business owner selling a company for $5,000,000:
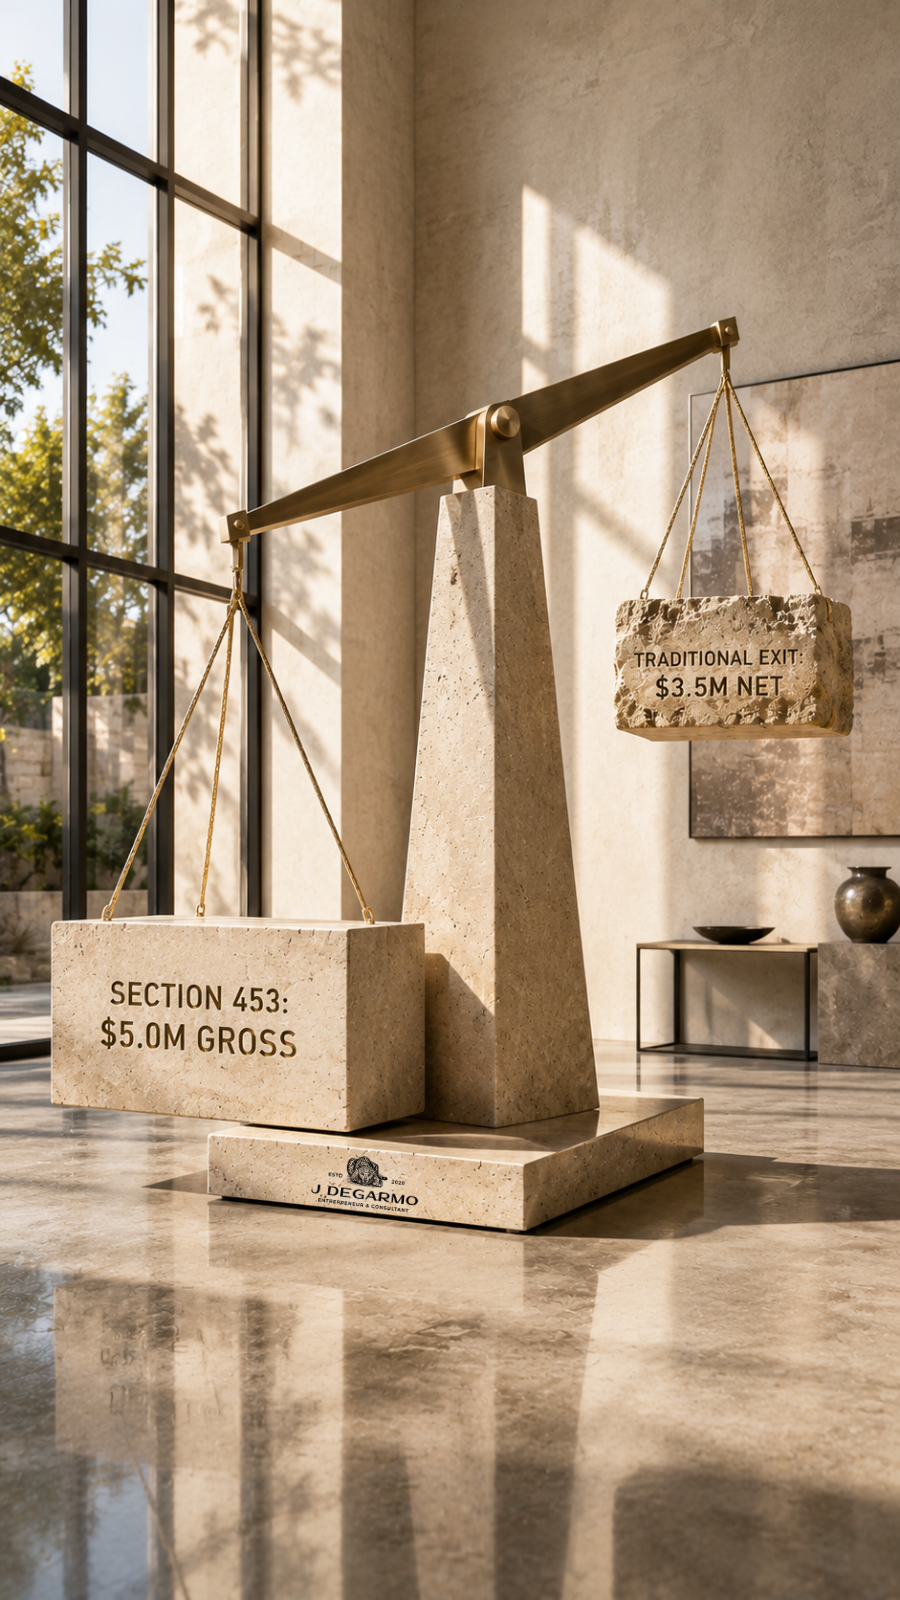
- Under a Traditional Sale: The owner pays immediate federal capital gains and surtaxes, shrinking the investable principal down to roughly 3.5M–3.8M on day one. Future investment returns compound only on this reduced net amount.
- Under a Structured Section 453 DST Exit: Capital gains recognition is deferred. The entire $5,000,000 gross purchase price remains deployed. Earning an annual yield on the full $5M principal produces significantly higher cumulative cash flow and long-term wealth compared to investing net proceeds after upfront taxes.
Risks and Compliance Considerations
While a Section 453 DST is a powerful wealth-preservation vehicle, it requires precise legal and tax execution:
- Branded Strategy, Not an IRS Acronym: “Deferred Sales Trust” is a financial product name, not a formal term in the Internal Revenue Code. The structure relies directly on core Section 453 installment sale rules.
- Strict Trustee Independence: The trustee must be entirely independent. If you retain direct control over the trust’s bank accounts or investment selections, the IRS can invoke the “constructive receipt” doctrine and demand immediate payment of all capital gains taxes.
- IRS Scrutiny: Tax authorities closely examine installment arrangements. The entire process must maintain genuine economic substance and be fully established before binding purchase contracts are finalized.
Why You Need an M&A Advisor to Execute This Strategy
Structuring a transaction for maximum after-tax value requires far more than listing your company on the market. It demands an advisory team that understands how to coordinate with qualified trustees, tax attorneys, and CPA specialists well before closing agreements are signed.
As your business broker, my role extends beyond finding the right buyer. I guide you through advanced transaction design, ensuring your deal is structured for maximum capital efficiency, full tax compliance, and long-term wealth preservation.
Contact me today to discuss how we can position your company for sale while protecting your proceeds through structured exit strategies.